Start with the payment rail, then the app
UPI connects participating bank accounts; PhonePe and Google Pay are interfaces that can use that rail. Choosing another app does not necessarily create a different payment route. A card payment instead depends on the card network, issuer and acquiring arrangements. A bank-transfer label may cover more than one transfer system, while a cryptocurrency payment requires both an asset and a network.
The useful comparison is therefore operational: which identifier follows the payment, who can investigate it, and in which currency does the receiving ledger record it? For an existing transaction, the receipt matters more than the logo displayed beside the cashier button.
Published limits are method-specific
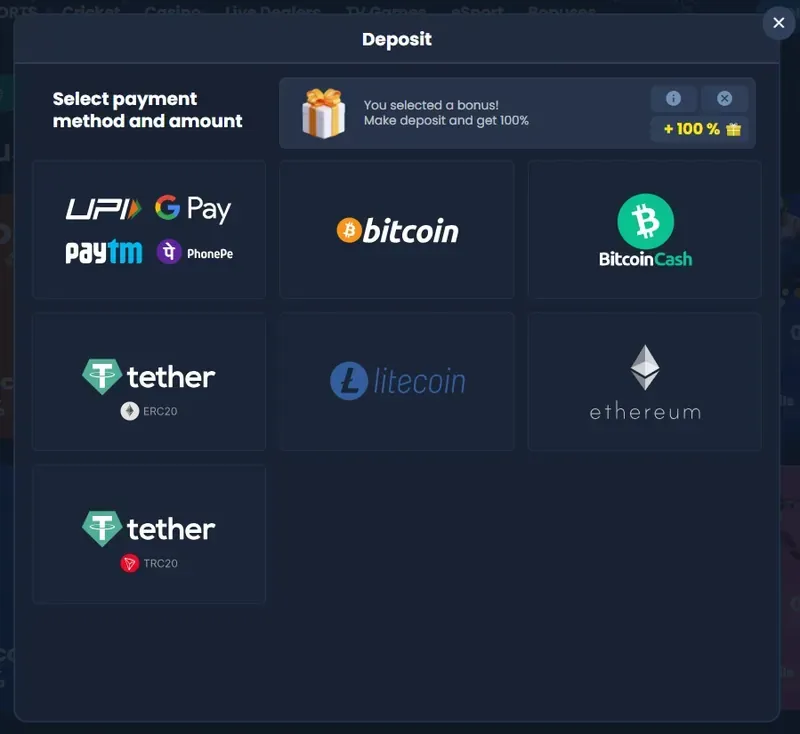
The operator’s public deposit guide lists the following INR ranges. They describe published product information rather than permission to transact from India. The India legal guide explains the national restrictions; a familiar payment method does not override them.
| Published method | Minimum | Maximum |
|---|---|---|
| UPI | ₹100 | ₹100,000 |
| Visa / Mastercard | ₹500 | ₹100,000 |
| Local bank transfer | ₹500 | ₹300,000 |
A quoted maximum is not a promise that every account, bank or payment order can use that amount. It also does not establish a daily limit or a withdrawal limit. Match the figure to its operation and currency before comparing two screens. A promotional qualifying deposit can be higher than the ordinary payment minimum; the bonus guide treats that requirement separately.
Compare the debit with the usable credit
A small reconciliation example
| Entry | Illustrative amount | Meaning |
|---|---|---|
| Payment instruction | ₹2,000 | The amount requested |
| Bank debit | ₹2,025 | Includes a separately recorded ₹25 charge |
| Cash account credit | ₹2,000 | Excludes any promotional credit |
| Bonus credit | ₹500 | Separate conditional balance |
These figures are an accounting illustration, not current fees or an offer. In this example the extra ₹25 is visible on the bank side, while the ₹500 bonus must not be used to claim that the payment produced a ₹500 profit. If a conversion occurs, preserve the original currency and rate as well. Comparing only a combined wallet total can hide the difference between cash, promotion and an unsettled amount.
The identifiers that make an investigation possible
- UPI: preserve the transaction reference or UTR exactly as shown, with payer, recipient, amount and status.
- Bank transfer: record the transfer system, beneficiary and bank reference; “bank transfer” alone is insufficient.
- Card: retain the masked card, posted amount and transaction date. Do not send the full number or security code.
- Crypto: retain the asset, network, destination, transaction hash and platform order number.
A bank marking a payment successful and a platform crediting the account are separate events. One institution may need the payment reference while the other first needs its order ID. A clean case contains both. The deposit reconciliation guide shows how to assemble that timeline without creating a second payment.
A status screenshot should include the transaction date, not only the word successful. The same amount may have been sent more than once, and support needs to distinguish the records. Keep the case number alongside the payment reference so a later reply can be matched to the correct transfer without reopening the entire history.
Crypto adds a second layer of accounting
Token units and INR are separate measurements
BTC is bitcoin, ETH is ether, and USDT is a token issued on several networks. A USDT label without its supported network is incomplete. The sender and recipient must support the same asset-network combination. An address that looks familiar does not prove compatibility, and a token contract address is not a customer’s deposit address.
Suppose a record shows 24 USDT arriving and a historical conversion quote of ₹84 per unit: 24 × 84 equals ₹2,016 before any additional deductions. The example illustrates multiplication, not a live exchange rate. A subsequent sale can use a different rate. Exchange withdrawal charges, network charges and conversion spreads also belong to different stages; do not combine them into an unexplained “platform fee”.
Build one payment record before requesting help
- Save the original receipt and the account ledger entry.
- Write the amount and currency at every stage, including any separate fee.
- Add the exact reference, order ID and timezone to a chronological note.
- Identify the unresolved stage: sending, delivery, reconciliation or return.
- Use the authenticated support route and retain the case number.
Never include a UPI PIN, password, one-time code or wallet recovery phrase in an attachment. Redact unrelated transactions while keeping an untouched original privately. If the issue concerns money leaving the gaming account, use the withdrawal guide; its review, dispatch and receipt stages differ from a deposit. A missing method is not a reason to use a private payment agent or a replacement account sent through an unsolicited message.
Questions answered
Are published deposit limits also withdrawal limits?
No. Each operation has its own terms. A ₹100 UPI deposit minimum does not establish a ₹100 withdrawal threshold.
Does a UPI logo confirm India availability?
No. A logo describes a payment-related claim, not legal eligibility, bank acceptance or a completed account transaction.
Which amount should match my bank debit?
Compare the cash deposit entry and separately recorded charges. Keep bonus credit and currency conversion distinct.
Can an explorer prove the account was credited?
It can show a network transaction. The receiving service must still identify it and apply its own crediting rules.